US
US scale-ups & subsidiaries
Delaware C-Corps, US groups, SaaS scale-ups (Series A–C). We bridge French GAAP to US GAAP / IFRS, model RSU and BSPCE plans, prep your Big 4 group auditor pack.
By Samuel Hayot — chartered accountant (OEC Paris–IDF) + statutory auditor (CRCC) · 12+ years serving international groups in France · Updated
Hayot Expertise is an English-speaking accountant in Paris: a French chartered firm (OEC + CRCC) working entirely in English with international businesses, French subsidiaries of foreign groups and scale-ups. Statutory accounting, IFRS bridge, payroll, VAT, R&D tax credit and audit sign-off — same firm, same English-speaking partner. Paris office, remote-first model across France and Europe.
What you get in those 10 minutes
In short
An English-speaking accountant in Parisis a French chartered accountant (expert-comptable, OEC + CRCC) who keeps your French entity's statutory books and delivers every report — monthly close packs, board memos, VAT and tax filings — in English. Hayot Expertise works exclusively with businesses that have a French legal entity: foreign-headquartered groups, international scale-ups and French companies with non-French boards. We do not handle individual expat personal tax returns. Delivery is remote-first through Pennylane: businesses in Paris and across France get the same service and the same fixed fee in every French department.
B2B-only positioning. We work with groups headquartered abroad and their French entities — not individual expat personal tax returns.
Delaware C-Corps, US groups, SaaS scale-ups (Series A–C). We bridge French GAAP to US GAAP / IFRS, model RSU and BSPCE plans, prep your Big 4 group auditor pack.
PLC / Ltd companies setting up French operations after Brexit. We handle VAT registration, post-Brexit OSS / IOSS, A1 certificates for cross-border employees and UK GAAP to French statutory bridge.
GmbH / AG groups expanding into France. HGB-to-French-GAAP reconciliation, transfer-pricing files aligned with Verrechnungspreise documentation, monthly board packs in English (or German on request).
Israeli HQs with French R&D centres and SaaS sales offices. CIR (R&D credit up to 30%), JEI status, Pennylane multi-entity views, coordination with OCS and tax authority in English.
Also serving groups headquartered in Switzerland, Belgium, the Netherlands, Italy and Spain, and French entities whose boards work in English wherever they sit.
Every French chartered accountant can keep your books. The point of choosing an English-speakingone is not the credential — it's what changes in your day-to-day operations, your group reporting, and your due-diligence readiness. Here's what a bilingual partner removes from your calendar and your risk register.
No translator between your CFO and your French accountant. No "lost in translation" on a transfer-pricing memo, no ambiguous email thread on a tax position. You read what we write, you reply, we act — same day.
Monthly close pack, board memo, tax-audit response, transfer-pricing dossier — every document drafted in English. Your PwC London or KPMG New York team consumes them without a re-translation step.
URSSAF, CFE, CIR, BSPCE, article 155 B, liasse fiscale 2065, Greffe — none of these mean anything to a US or UK director. We explain each one in terms you already use (payroll tax, R&D credit, stock plan, corporate tax return, companies house).
We pick up the phone in English with your US tax preparer, your UK auditor, your German group controller. No game of telephone, no slowdown on treaty positions, foreign tax credits or intercompany eliminations.
You don't get a French-speaking junior who escalates anything complex. Samuel Hayot — chartered accountant + statutory auditor (OEC + CRCC) — owns your file directly. Slack, Teams, email, video — all in English, all with the same person.
When you raise, exit or pass an audit, the buyer's diligence team reads every memo, every position, every contract in English from a single repository. No translation sprint at the worst possible moment.
Why I built this practice
I'm Samuel Hayot — French chartered accountant (Expert-Comptable, OEC Paris) and statutory auditor (Commissaire aux Comptes, CRCC). For 12+ years I've watched foreign-headquartered groups in Paris pay French firms twice: once for the work, once for the translation. I built Hayot Expertise so that the English-speaking founder, the US group controller, the UK board chair never again receive a tax-audit notification they can't read on their phone.
The point isn't that I speak English. The point is that my entire workflow — close pack templates, memo library, audit-response routines, tax authority correspondence — runs in English by default. French version included, never the other way around.
Four checks separate a firm that genuinely works in English from one that merely takes calls in English. First, verify the registration: only an expert-comptable listed in the public directory of the Ordre des experts-comptables may legally keep books for third parties in France. Second, ask for a sample deliverable: "English spoken" on a website says nothing about the language of the monthly close pack. Third, if you report to a parent company, test group-reporting capability (IFRS or US GAAP bridge, intercompany files). Fourth, require a fixed fee in writing: the engagement letter (lettre de mission) is mandatory in France and should leave no room for hourly surprises.
The table sums up what changes in practice between a traditional French-first firm and an English-first model like ours.
| What to compare | Typical French-first firm | English-first firm (our model) |
|---|---|---|
| Monthly close pack | French statutory formats; your team translates for the group | Drafted in English by default, French statutory version included |
| Who answers your group auditor | You do, after a translation round-trip | We do, directly, in English |
| Translation cost and delay | External translation billed on every memo and board pack | None: board, controller and auditors consume deliverables as-is |
| Tax-authority letters | Forwarded to you raw, in French | Explained in plain English with a recommended action |
| Pricing model | Often hourly, with year-end surprises | Fixed fee agreed in writing before the engagement starts |
If your group operates day-to-day in French and mainly needs a regulated expert-comptable for a foreign-owned entity, our French-first service is the better fit: see French CPA for foreign companies.
Our hub is built for companies that already have — or are creating — a legal entity in France. We work in English daily with foreign groups, scale-ups and bilingual founders. Individual expat personal-tax matters (US-France treaty, FBAR) sit in our dedicated practice.
You are a US, UK, German, Swiss or Israeli group launching a SAS, SARL or branch in France. We handle incorporation at the Greffe, VAT registration, social contributions onboarding (URSSAF, AGS) and the first English-reported closing — all coordinated with your global CFO and legal counsel.
See entity setupSeries A to C with founders or boards based outside France. We manage statutory accounting, payroll for French and impatriate employees, R&D tax credit (CIR up to 30%), VAT one-stop-shop and quarterly board packs. Pennylane multi-entity views give your finance team live consolidation data.
Explore startup supportYou run a French SAS, holding or family office whose shareholders, directors or auditors operate in English. We deliver every deliverable in both French and English: statutory accounts, board packs, transfer-pricing memos, year-end auditor coordination — without translation gaps or duplicated work.
Holding & investor reportingOur infrastructure — IFRS bridges, parent reporting, intercompany files and in-house audit sign-off — is built for a real French entity that has to satisfy a global CFO, a board and a group auditor in English. That focus is what makes us the right partner for a group, and an honest mismatch for a simple individual filing.
If you only need a personal income-tax return, an online volume firm will serve you faster and more cheaply, and that is a different job. We deliberately specialise so the work a scaling group needs is done by the same English-speaking partner from day one.
Every close ships with a French-GAAP-to-group-standard reconciliation. That machinery is built for an entity consolidating into a parent — not for a one-off personal return.
Monthly board packs, intercompany breakdowns and multi-currency views, delivered in English for a group finance function.
Documented management fees, royalties and cost-plus arrangements aligned with OECD guidelines — a B2B discipline, not a consumer service.
When a scaling entity crosses the audit thresholds, our CRCC-registered auditor signs off — same firm, same English-speaking partner.
Need a personal US-France return (1040, FBAR, FATCA)? That is a different job — see our dedicated US-clients practice.
Searches for an English-speaking accountant mix two very different needs: running a company and filing personal taxes. Here is the honest routing, so you land with the right specialist first time.
You invoice through your own SASU or EURL and need books, VAT and payslips handled in English. That is squarely in scope: the same fixed-fee model applies from a one-person company upwards, with the same partner and the same SLA.
Personal US-France tax is a different job from company accounting, with its own treaty mechanics and its own workflow.
See our practice for US clients in ParisIf you are an employee with no company and simply need the annual French return filed, we are honestly not the right fit: a volume online firm will serve you faster and at lower cost. Bookmark us for the day you incorporate.
Every deliverable comes in both French (for legal filings) and English (for your group, board and auditors).
Bookkeeping under French GAAP (PCG), monthly closings, annual statutory accounts (liasse fiscale 2065), filing at the Greffe — explained in English so your parent company and auditors stay in control.
Reconciliation French GAAP → IFRS or US GAAP, monthly reporting packs in your group template, intercompany eliminations, multi-currency views. We talk directly with your group controller.
French VAT registration, intra-EU OSS/IOSS returns, corporate tax (IS) optimisation, transfer-pricing documentation aligned with OECD guidelines, withholding tax on dividends and royalties.
Payslips, DPAE, employment contracts, BSPCE plans, payroll for impatriate executives (article 155 B CGI), expat health & retirement schemes, redundancy modelling — full English documentation.
Eligibility review for CIR (30% of R&D spend) and CII for SMEs, dossier preparation, defence in case of tax audit, JEI / Young Innovative Company status. Particularly relevant for tech and biotech subsidiaries.
When your French entity exceeds the audit thresholds, our CRCC-registered auditor signs off your accounts — same firm, same English-speaking partner, no hand-off to a third party.
Most French firms hand you a French-GAAP balance sheet and let you do the bridging. We don't. Your monthly close lands in your group template, in your reporting standard, with the footnotes and intercompany breakdown your global CFO expects.
We talk directly with your group controller, not through a translator. Quarterly board calls in English are part of the engagement — same partner, no escalation chain.
Group reporting template
We map French GAAP accounts to your group P&L, balance sheet and cash-flow lines from day one.
IFRS / US GAAP bridge
Lease accounting (IFRS 16), revenue recognition (IFRS 15 / ASC 606), goodwill — explicit reconciliation memo each close.
Multi-currency P&L
Pennylane multi-entity and multi-currency views give your finance team live consolidation data.
Intercompany & transfer pricing
Documented management fees, royalties, cost-plus arrangements aligned with OECD guidelines.
Auditor coordination
We deal directly with PwC, EY, KPMG, Deloitte, Mazars and Grant Thornton on your group audit requests.
A snapshot of the typical situations we resolve every quarter for international clients. Each row maps the French statutory treatment to the parent-reporting impact and our usual delivery cadence.
| Situation | French statutory treatment | Group-reporting impact | Typical timing |
|---|---|---|---|
| New US sub, year 1 losses | Carry-forward losses indefinitely under IS | IFRS deferred tax asset memo for parent close | Closing + memo within 30 days |
| UK group, dividend up-stream | Withholding tax under the France–UK tax treaty (Art. 11) since Brexit; 0% only where Art. 119 ter CGI conditions are met — fact-dependent, not automatic | Booking timing for parent close, treaty form completion | Quarterly |
| German Mittelstand acquisition | PPA under French GAAP + goodwill impairment test | HGB-to-IFRS bridge memo, group consolidation note | Within 12 months of acquisition |
| Multi-country VAT (OSS / IOSS) | OSS registration via French portal | Single quarterly return, transaction-level export to parent ERP | Quarterly |
| French entity exceeds audit thresholds | Statutory audit (CAC) mandatory — sign-off filed at Greffe | In-house CRCC partner — same firm, no hand-off to a third party | Within 6 months of FY end |
Indicative summary. Each engagement is scoped against your actual group structure, fiscal year and parent-reporting standard.
If you set up a French SAS or moved to Paris as an executive, the impatriate regime (article 155 B of the French Tax Code) can exempt up to 50% of your impatriation premium from income tax for eight years. We handle the company side: payroll, BSPCE plans, dividends, social contributions on directors' salaries.
Personal tax filings (US Form 1040, FBAR, FATCA, UK self-assessment) are handled by partner firms we coordinate with — or our dedicated practice for US clients in Paris.
Anonymised client case
VP Engineering, US tech scale-up — Paris assignment 2024
€240,000 total compensation
Representative case based on a 2024 engagement. Actual savings and operational figures depend on individual compensation, family status, foreign-workdays share, entity complexity and the state of the prior firm's records.
The tax saving above sat alongside an operational one. Here is what changed for the US subsidiary's finance function once reporting moved into English.
Before
After Hayot Expertise
From discovery call to first English close pack in five working days.
A focused 10-minute video call in English with Samuel Hayot. We map your group structure, flag your immediate French compliance bottlenecks, and hand you a definitive action plan — before any quote or commitment.
Fixed-fee proposal in English (or French + English) detailing scope, deliverables, SLA and review cadence. No hidden hourly billing surprises.
Pennylane and Dext set-up, banking integrations, recovery of historical accounts, introductions to URSSAF / DGFiP / Greffe contacts, payroll cut-over.
English monthly close pack, quarterly board call with your group controller, annual statutory accounts, year-round Slack / email support under 24h.
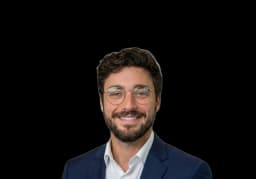
Hayot Expertise is deliberately partner-led. Samuel Hayot, chartered accountant ( OEC Paris–IDF) and statutory auditor ( CRCC), owns every file personally: the person who answers your Slack message is the person who signs your statutory accounts. No juniors learning on your dossier, no call-centre, no escalation chain.
In a market where larger firms rotate staff every year, that continuity is the point: your group's history, tax positions and reporting quirks stay in one head, in English, year after year.
Our office is in Paris 8 (Monceau) but our delivery model is remote-first. Through Pennylane multi-entity views, Dext for receipt capture and Slack / Teams for daily collaboration, we serve French subsidiaries of foreign groups regardless of where in France the entity is registered.
In practice, our clients are headquartered in Paris, Lyon, Bordeaux, Marseille, Nice, Toulouse, Lille, Nantes, Strasbourg and Rennes — plus a long tail of clients with no physical French staff (registered office at our address). Quarterly board calls happen on video; in-person meetings in Paris are always available.
For statutory in-person obligations (capital deposit, Greffe filings, tax-audit hearings, URSSAF on-site audits), we coordinate locally — either directly when the entity is in Île-de-France, or via our partner network of OEC-registered firms in the relevant department.
Paris HQ
58 rue de Monceau, 75008 — main office, daily walk-in availability
Île-de-France
Direct in-person coverage across all 8 departments
Rest of France
Remote-first via Pennylane / Dext / Slack — same SLA, same partner
Cross-border
EU clients (DE, IT, ES, BE, NL) and UK / US / IL groups — async-friendly workflow
For groups that want a face-to-face partner in addition to remote delivery. In-person meetings available at all three locations.
58 rue de Monceau, 75008 Paris
Métro Monceau (2) · Courcelles (2)
Walk-in availability Monday–Friday for foreign-group teams visiting Paris.
Seine-Saint-Denis, eastern Paris metro
RER E · Tram T1
Second office serving clients in the 93 / 94 / 77 departments.
Côte d’Azur — southern France
Cannes city centre
Riviera coverage for tech founders, hospitality groups and EMEA-based executives.
Most searches for English-speaking accountants in France surface Paris firms and expat directories. In practice, location matters far less than registration: any expert-comptable registered with the Ordre can act for an entity registered in any French department, and our delivery model is built for exactly that. Bookkeeping runs on Pennylane, documents flow through Dext, meetings happen on video, and the fixed fee is the same whether your company is registered in Paris, Lyon, Bordeaux or a village in the Dordogne.
What is genuinely hard to find are accountants in France who work in English as their default deliverable language, and who keep the same interlocutor as you grow. Here, the partner who signs your accounts stays your direct contact wherever the entity is registered; statutory in-person obligations (capital deposit, Greffe filings, tax-audit hearings) are coordinated locally through our network of OEC-registered correspondent firms.
All packages are fixed-fee and exclude VAT (20%). No hidden hourly billing.
from €390 / month
New French subsidiary, < €500k revenue, 0–5 employees
from €890 / month
Scale-up, €0.5–10M revenue, 5–30 employees
on quote
Multi-entity French perimeter, > €10M revenue or > 30 employees
The French accounting and tax terms that come up in every initial call with a foreign group, explained in one line each so your global CFO does not need a translator.
The four 2026 changes we brief every international client on, and what to do about each.
Every French-established company must be able to receive electronic invoices through a government-accredited platform (PDP) from 1 September 2026. Issuing becomes mandatory the same day for large and mid-size companies, and on 1 September 2027 for SMEs. Action: connect the entity to a PDP (we run this through Pennylane) and verify its entry in the central directory.
The French flat tax (PFU) on dividends and interest paid to individuals rises from 30% to 31.4% in 2026, following the CSG increase in the 2026 social-security financing law. It concerns founder-shareholders resident in France; dividends up-streamed to a foreign parent follow tax treaties and the EU Parent-Subsidiary Directive instead.
Small entities stay outside VAT below €37,500 of services or €85,000 of goods per year (the planned single €25,000 threshold was abandoned). Relevant for a first French entity in its opening months and for solo founders: crossing the ceiling mid-year triggers registration.
The French minimum wage is €12.31 gross per hour since 1 June 2026, about €1,867 gross per month full-time. Employer social contributions come on top and vary sharply with salary level, so ask for a full employer-cost simulation before budgeting a first French hire.
Calendar-year entities — adjust by ±1 month for fiscal-year filers.
1 September 2026
E-invoicing: every French-established company must be able to receive electronic invoices through an accredited platform (PDP)
15 December 2026
CFE (local business tax): annual payment deadline
4 May 2027
Corporate tax return (liasse fiscale 2065) for FY 2026: second working day after 1 May, +15 calendar days when filed electronically
30 June 2027
AGM approving the FY 2026 accounts (6 months after close); Greffe deposit due within the following month (two months if filed online)
15th–24th of each month
VAT return (régime réel normal): exact day set by the DGFiP filing schedule
Quarterly
Transfer-pricing documentation review
39 real reviews across our two offices · pulled live from the Google Places API
Our clients share their experience with our firm.
A monolingual French accountant is not a neutral choice for a foreign-born director: impatriate regime under-claimed, board minutes misread, board pack ignored. What a genuinely bilingual French practice actually changes in 2026.
Read the articleA Paris-based practice's method for choosing an English-speaking accountant in France: verify the credential with the Ordre, separate bilingual delivery from 'someone speaks English', match the profile to your situation, plus the 10 questions to ask.
Read articleParent-subsidiary regime, French tax consolidation, ATAD, withholding taxes: how to structure a French holdco with an EU subsidiary to scale cleanly in 2026.
Read articleMaster file, local file, Form 2257-SD, CbCR: everything a French SME must produce to secure its 2026 transfer pricing position, with a checklist and decision trees.
Read articleHiring a foreign employee in France in 2026: work authorisation, residence permits, the talent card and illegal-work penalties. The employer's guide.
Read articlePosting an employee abroad in 2026: the A1 certificate, keeping French social security, payroll and the difference from expatriation. The step-by-step method.
Read articleLLC, C-Corp or French parent's US subsidiary: three vehicles, three tax outcomes both in the US and in France. The 2026 decision guide for French SME owners and startup founders.
Read articleFrom foreign founders, group controllers and finance directors who hired us.
No — we are a French chartered accounting firm registered with the Order of Chartered Accountants (OEC Paris–IDF) and the National Auditor body (CRCC). This is the European equivalent of a CPA practice and is the qualification recognised by the French tax authorities to sign your statutory accounts.
Yes. We produce a monthly bridge between French GAAP and your group reporting standard (IFRS, US GAAP or a custom group template). We talk directly with your group controller and deliver the pack inside Pennylane or as Excel exports.
Yes — every monthly close pack, board memo and reporting deliverable is drafted in English by default, with the French statutory version included. Your group controller, board and auditors consume them as-is, with no re-translation step.
Yes. We speak directly in English with your US tax preparer, UK auditor or group controller on treaty positions, foreign tax credits, intercompany eliminations and group audit requests. No intermediary, no game of telephone — which is what keeps cross-border closes on schedule.
We sign and file the statutory accounts in French (legal requirement at the Tribunal de Commerce) and provide the English version of every deliverable for internal use, board approval and parent reporting.
Five working days for a clean set-up: 10-Minute Diagnostic Flash, engagement letter, Pennylane and Dext configuration, banking integrations, payroll cut-over. If we recover historical accounts from another firm, count two to four weeks for the full migration.
Yes. A large share of our clients have no physical team in France — the entity is registered at our address or domiciled, and we run the full accounting, VAT and statutory cycle remotely via Pennylane, Dext and Slack / Teams. Your group still gets the same monthly English close pack and the same SLA.
Yes. We coordinate the SAS, SARL or branch creation with the Greffe, draft the bylaws in French (with English translation), file the immatriculation, set up the share-capital bank account and register the company for VAT and social contributions.
Yes. Impatriate executives can benefit from up to 50% income-tax exemption on their impatriation premium for eight years. We model the saving, run the dedicated payslips and produce the documentation required by the tax authorities.
Yes, and it is the partner himself. Samuel Hayot, the chartered accountant and statutory auditor who signs your accounts, owns your file personally. You always reach the same person on Slack, Teams or email: no rotating call-centre, no junior handoffs, no escalation chain.
Our packages start at €390 per month for a new subsidiary and scale to €1,890+ per month for groups with parent-reporting and audit requirements. Pricing is fixed-fee, agreed upfront in writing, with no hourly surprises.
Yes. We are a Pennylane Premium partner and integrate Dext for receipt capture, Stripe / Mollie / Adyen for revenue, Qonto / Revolut / BNP for banking, and Spendesk / Pleo / Ramp for expense management.
Yes. We prepare the documentation requested by the French tax authorities, attend the meetings on your behalf, and negotiate the closing position. Two of our clients went through full corporate-tax audits in 2025 with €0 reassessment.
Our hub serves businesses with a French legal entity. For individual expat tax matters (US-France treaty, FBAR, FATCA, ITIN), we run a dedicated practice — see our Saint-Germain-en-Laye and Paris US-clients page.
Main office: 58 rue de Monceau, 75008 Paris (five minutes from Monceau and Courcelles métro). Second office: Noisy-le-Sec (Seine-Saint-Denis, eastern Paris metro). Riviera office: Cannes — for clients in southern France. We welcome in-person meetings at any of the three and also work fully remotely across France, Europe and the US.
Four rates apply in mainland France: standard 20% (most goods and services), intermediate 10% (restaurants, transport, tourism), reduced 5.5% (books, food, energy), and super-reduced 2.1% (medicine, press). Intra-EU B2C sellers use the One-Stop-Shop (OSS) regime — single quarterly return for the whole EU. We handle TVA registration, monthly or quarterly returns and OSS / IOSS for foreign-group subsidiaries.
The fiche de paie is the statutory French payslip — every employee receives one each month. It must list gross salary, employee and employer social-security contributions, withholding income tax (prélèvement à la source), net taxable salary and net pay. We run monthly French payslips on Silae with highly-automated imports — variable elements, expense claims and HR feeds flow in without manual re-keying — plus an optional English translation appendix for your foreign HR team.
Standard rate is 25% on all corporate profits since 2022 (one of the lowest in mainland Europe). Reduced rate of 15% applies to the first €42,500 of profit for SMEs with revenue under €10M and at least 75% individually-held capital. Withholding-tax exemptions exist for dividends remitted under the EU Parent-Subsidiary Directive and most bilateral tax treaties.
The same as in Paris, at least with us: fees are driven by transaction volume, payroll headcount, VAT regime and the group-reporting standard, not by geography. Remote-first delivery means one fixed fee in every French department. Whatever firm you choose, insist on the written fixed-fee quote in the engagement letter before committing.
Yes. We advise pre-incorporation on the structure (subsidiary versus branch), register foreign companies for French VAT without an establishment where the activity requires it (EU companies directly, non-EU companies through a fiscal representative), and set up payroll for a French-based employee without an establishment through the dedicated URSSAF scheme for foreign firms.
No law forces a company to appoint one. The legal obligations are to keep compliant books, file the annual accounts and tax returns in French, and appoint a statutory auditor above certain thresholds. Foreign groups appoint a chartered accountant anyway because the expert-comptable is the only profession legally allowed to keep books for third parties, and because getting French filings wrong is expensive.
Yes, at any point in the fiscal year. Notice is contractual (typically three months in the engagement letter; there is no statutory notice), and the handover runs accountant-to-accountant under French professional rules: we send the confraternal takeover letter, recover the ledgers (FEC file), balances and permanent file, and reconcile before the next close. The smoothest switch follows an annual return, but mid-year transfers are routine.
Four things. E-invoicing: from 1 September 2026 every French-established company must be able to receive electronic invoices through an accredited platform (PDP). The flat tax on dividends paid to individuals rises to 31.4%. The VAT franchise thresholds are confirmed at €37,500 (services) and €85,000 (goods). And the minimum wage (SMIC) is €12.31 gross per hour since 1 June 2026.
Check the public directory of the Ordre des experts-comptables (annuaire.experts-comptables.org): every legitimate firm and partner is listed with its registration. For statutory audit work, check the CNCC directory as well. Then test the English-speaking claim itself: ask for a sample monthly close pack in English. Many accountants in France speak English on calls but still deliver everything in French.
No obligation, no slide deck. In 10 minutes we map your group structure, flag your immediate French compliance bottlenecks and hand you a definitive action plan.
58 rue de Monceau, 75008 Paris · 06 51 47 43 92

Chartered Accountant, registered with the Institute of Chartered Accountants. Certified Pennylane trainer.
Regulated French accounting and audit firm based in Paris 8, built to support companies across France with a digital and decision-oriented approach.
Official and operational sources cited for this page.


